Global infrastructure briefing · July 2026
Inside the world’s data centers
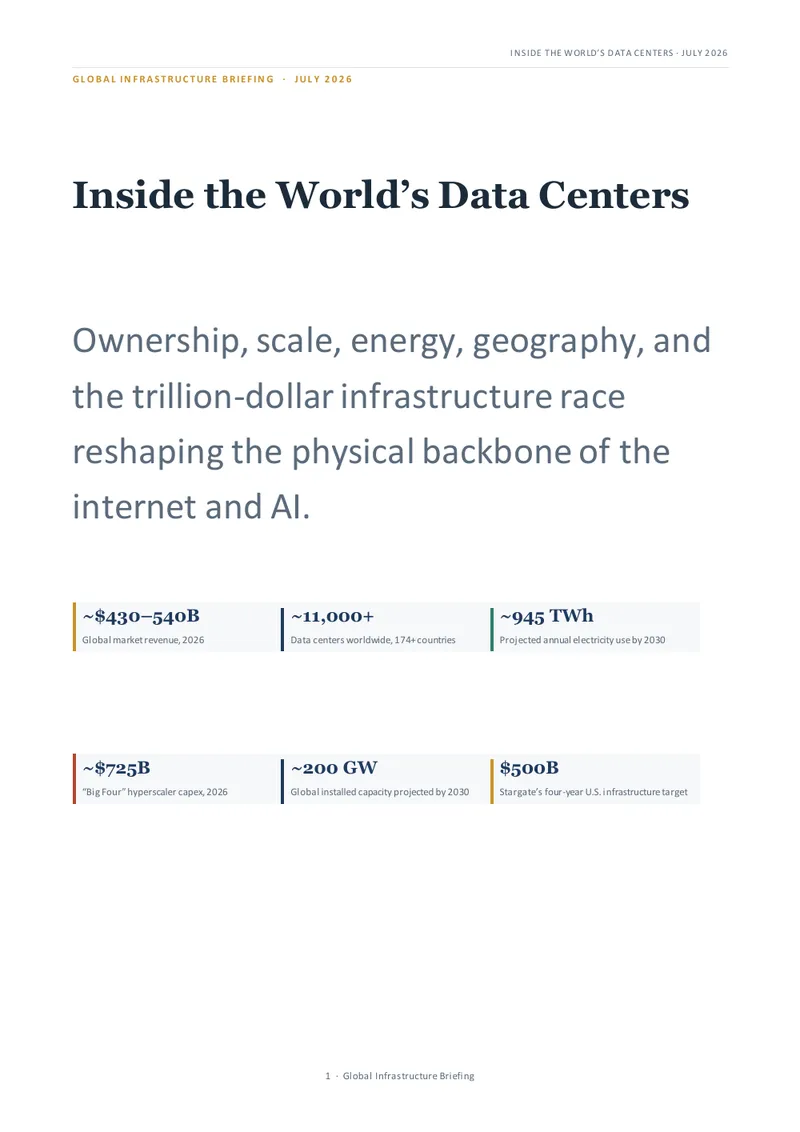
Ownership, scale, energy, geography and the trillion-dollar infrastructure race reshaping the physical backbone of the internet and AI.
Summary
Data centers have quietly become one of the largest capital-construction categories on the planet. What used to be anonymous warehouses full of servers are now gigawatt-scale industrial campuses, financed like power plants, sited like factories and watched as closely as any commodity market.
This 15-page briefing pulls together the latest available statistics, as of mid-2026, on who owns the world’s data centers, where they sit, how big they are, how much power and water they use, and who is financing the AI build-out.
For sustainability teams the conclusion is practical: power, not chips, is now the binding constraint. Electricity sourcing, cooling water and grid access decide where capacity can be built, and they belong in Scope 2 accounting, water-footprint work and climate-risk disclosure for every company that depends on cloud and AI infrastructure.
Inside the report
- The market at a glance
- Who owns the world’s data centers: hyperscalers, colocation REITs, AI-native builders, financial owners and China’s operators
- On land, underwater and everywhere in between
- The largest projects: Hyperion, Stargate Abilene, Prometheus, Project Rainier and others
- The latest trends: power is now the binding constraint
- Efficiency and cooling: PUE, liquid and immersion cooling, Germany’s PUE rules
- Who is paying: hyperscalers, AI labs, private equity, sovereign wealth funds and REITs
- Outlook